
Home / Industries
Merchant services by industry, set up for how you get paid.
Merchant services by industry start from one fact: a fuel station, a dental office and a county tax office don’t take payments the same way. We set up processing around where your customers pay, what data the card networks expect from you and which costs you can legally offset.
What changes by industry
| Where you take payments | Counter, table, pump, web, phone |
| How you get paid | Card, ACH, recurring, invoice |
| Data you send | Level I, II or III |
| Fees you can offset | Surcharge, convenience fee, cash discount |
| Equipment | Fitted to your POS or system |
Card-brand rules and state rules vary. We help you check current rules.
Industries we set up
Pick your industry to see the payment situations we handle, the questions owners ask us and the guides worth reading.
 Restaurants and cafésTableside, counter, catering
 RetailSingle store to multi-location
 GroceryHigh volume, fast lanes
 Medical and dentalRecurring and patient payments
 Government and utilitiesConvenience fees, online bill pay
 Petroleum and C‑storesPay at the pump and inside
 B2BLevel II and III data, invoicing
 Nonprofits and ministriesDonations and events
 Schools and day caresTuition and recurring billing
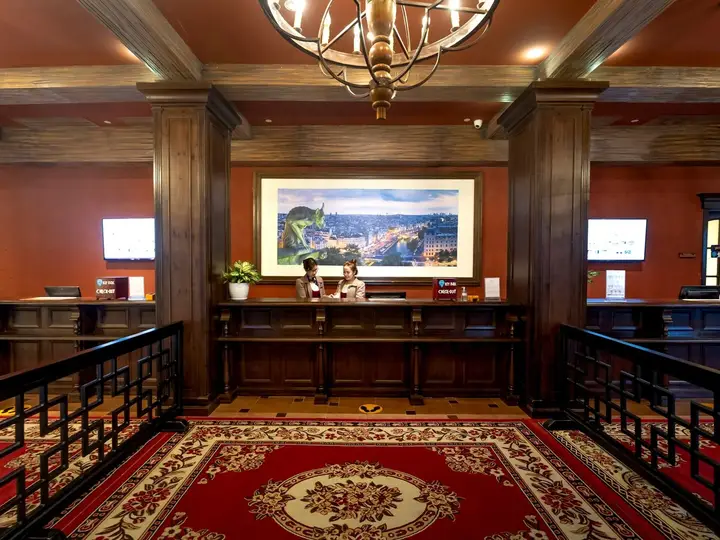 HospitalityFront desk to event venues
Why setup differs by industry
The card networks price and police payments differently depending on how a card is used. A chip card tapped at a grocery lane, a card number typed into a web form and a corporate card used to pay an invoice can each fall into a different interchange category. The rules for adding a fee, holding funds or adjusting a tip change too. A setup copied from another kind of business usually costs more than it should.
Where your customers pay
Some businesses take nearly every payment at one counter. Others take cards at the table, at the pump, in the stands, on a website and over the phone in the same day. Each place needs the right terminal, gateway or connection, and all of them should report to one place. See how this plays out for restaurants, fuel stations and hotels and venues.
How you get paid
A store gets paid at checkout. A school or a medical practice often gets paid on a schedule. A B2B company gets paid by invoice, sometimes by card and sometimes by bank transfer. Recurring billing, payment links and ACH matter more for some industries than others, and the right mix lowers the cost of getting paid.
Data you send and fees you can offset
Business customers paying with commercial cards can qualify for lower interchange when you send Level 2 and Level 3 data. Government offices often use convenience fees. Retailers and restaurants may look at surcharging or a cash discount program. Each follows its own card-brand rules, and some states add their own, so we help you check current rules before anything goes live.
What stays the same
Whatever your industry, you get Interchange-Plus pricing with our margin on its own line, no early termination fees, no non-compliance fees and a real person who answers when you call. Start with a free statement analysis and we will tell you exactly what you pay today.
Want a straight answer about your own statement?
Send us one recent statement. We line-item every fee and tell you what you are really paying. Free, no pressure.
Or call 866.242.4325. A real person answers.
Not only did PayZoom lower our costs, they analyzed our internal processes and made recommendations to improve workflow and provided new equipment so we could capture electronic payments at all points in the hospital and at off-site locations.
Jim Bishop, CPA, Controller, Jennie Stuart Medical Center
Since 2006, a person who knows your account.
| Founded | 2006, Daphne, Alabama |
| Clients in | Nearly every U.S. state |
| Support | Never outsourced |
| Registered partner of | Cygnus Payments and Evolv Payment Solutions |
Questions merchants ask us
Straight answers. If yours is not here, call us and a real person will answer it.
Why does my industry change my processing setup?
Because the card networks treat payments differently depending on where and how a card is used. A card-present sale, an online order and a commercial card invoice can each carry a different interchange cost and different rules. Your industry decides which of those you see most, so it shapes the equipment, data and pricing that make sense for you.
My industry isn’t listed. Can you still help?
Probably. The pages here cover the industries we see most, but PayZoom works with businesses in nearly every U.S. state and many kinds of operations. The same questions apply: where customers pay, how you get paid and what data you send. Send us a statement or call, and a real person will tell you what fits.
Do you sell industry-specific POS systems?
No. PayZoom doesn’t sell a proprietary POS. We are platform-agnostic, so we set up processing to fit the POS, gateway, shopping cart or industry software you already use where it is supported. If you need equipment, we can supply terminals and POS options from the hardware we carry.
Is pricing different for each industry?
Interchange is set by the card networks and varies with card type and how a card is accepted, so your costs depend on your mix. Our approach doesn’t change: Interchange-Plus, with our margin shown on its own line. Processing starts as low as 0.05% + $0.22 per transaction, depending on your setup.
Send us one statement. We’ll tell you exactly what you’re paying.
No cost and no pressure. If your current rate is fair, we’ll say so. We typically reply the same business day.
| Call toll-free | 866.242.4325 |
| Local | 251.626.8100 |
| nate@bizpayzoom.com |